A comparison of IAG and ELF reveals differing valuations in the insurance sector.
In the competitive landscape of the insurance sector, investors often seek value opportunities among established names. This analysis focuses on two prominent players: iA Financial Corporation Inc (IAG) and E-L Financial Corp Ltd (ELF). By examining key valuation metrics, we can see how these companies compare and what it might mean for potential investors.
Investor takeaway: While E-L Financial appears cheaper on several valuation multiples, this doesn’t necessarily mean it’s the better investment choice. Both companies carry a 'Strong Sell' consensus from analysts, highlighting the need for caution.
Advertisement
Stocks in this list
Live snapshots — open any name for the full quote and Wealth Awesome price forecast.
iA Financial Corporation Inc
IAG.TO
Financials
$201.99
$17.85B
1D
-0.97%
1W
-0.49%
E-L Financial Corp Ltd
ELF.TO
Financials
$17.64
$6.10B
1D
-0.06%
1W
+0.74%
Advertisement
Valuation Comparison: IAG vs ELF
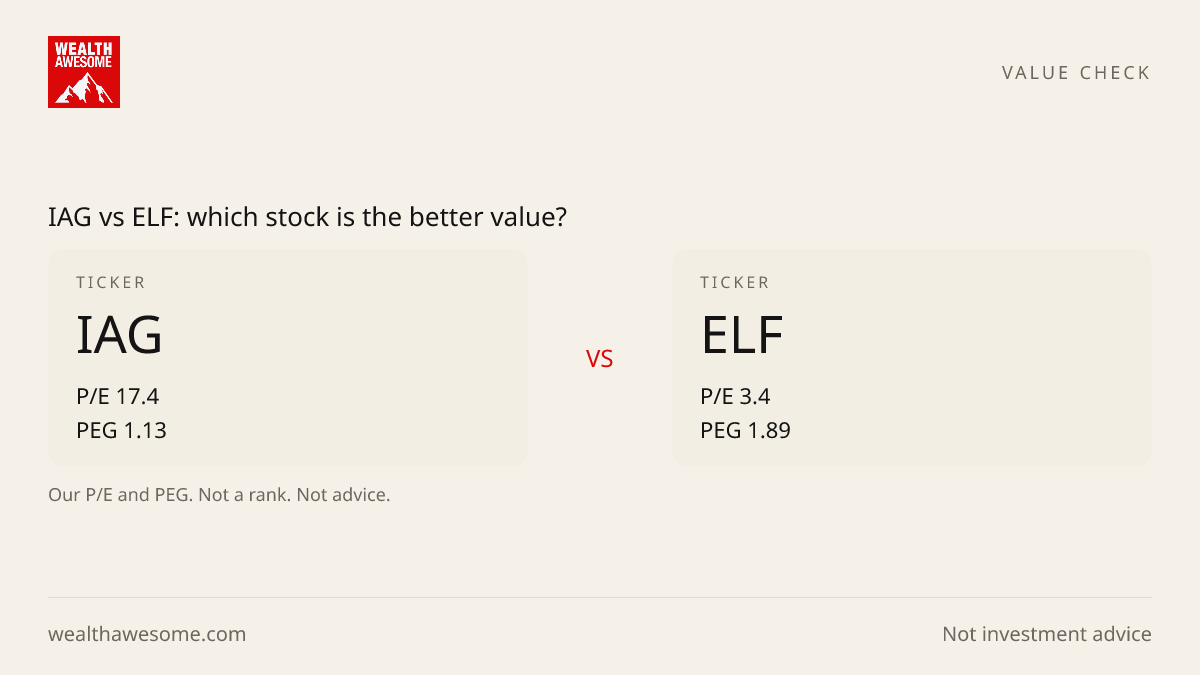
IAG has a P/E of 17.4, while ELF boasts a P/E of 3.4. In terms of P/B, IAG stands at 2.51 compared to ELF's 0.64.
Bull case
E-L Financial's significantly lower P/E ratio of 3.4 compared to iA Financial's 17.4 suggests it might offer better value for investors looking for bargains in the insurance sector. Plus, its higher return on equity (ROE) of 19.6% indicates it could be using equity capital more efficiently.
Bear case
Despite its attractive valuation metrics, E-L Financial's lower dividend yield of 0.91% compared to iA Financial's 2.05% may turn off income-focused investors. Additionally, both companies face a 'Strong Sell' consensus, indicating underlying concerns that could affect future performance.
Advertisement
Valuation Metrics Overview
When comparing IAG and ELF, the differences in valuation metrics are striking. iA Financial Corporation has a P/E ratio of 17.4, a PEG ratio of 1.13, and a P/B ratio of 2.51. In contrast, E-L Financial presents a much lower P/E of 3.4, a PEG of 1.89, and a P/B of 0.64. This comparison shows that E-L Financial is cheaper on most of these key multiples, which may attract value-seeking investors.
Dividend and ROE Analysis
In terms of dividends, iA Financial offers a yield of 2.05%, making it a more appealing option for income-focused investors compared to E-L Financial's yield of 0.91%. However, E-L Financial's ROE of 19.6% surpasses iA Financial's 13.9%, suggesting it’s using equity more effectively. This mixed performance highlights the importance of considering both growth potential and income generation when evaluating these stocks.
Best next step
Keep exploring this topic
If you want to go deeper, these are the most useful follow-up pages and tools for this topic.
Broker comparison
Best trading platforms in Canada
Compare $0-commission brokers before you act on a ticker story.
Safe cash
Best GIC rates in Canada
If the story makes you want to de-risk, compare guaranteed rates next.
HISA roundup
Best high-interest savings accounts
Keep dry powder in a no-fee savings account instead of chequing.
TFSA room
Check TFSA contribution room
Shelter the next contribution before you buy.
Advertisement
Wealth Awesome
Timely coverage of Canadian stocks, earnings, dividends, and market movers for DIY investors. Stories are checked against exchange data and public filings.
View Full Profile →✅ Reviewed by Certified Financial Professionals
This content has been reviewed by CFA® charterholders and Certified Financial Planners (CFP®) with over a decade of experience in Canadian financial markets. All information is fact-checked against official Canadian sources and regulations.
Why these credentials matter: CFA® charterholders complete 900+ hours of rigorous study in investment analysis and ethics. CFP® professionals are held to the highest standards of financial planning competency and fiduciary duty in Canada.
⚠️ Professional Disclaimer
This content is for educational purposes only and should not be considered personalized financial advice. While our team brings professional expertise, individual circumstances vary. For personalized guidance, consult with a qualified financial advisor, tax professional, or mortgage specialist.